What is the market overview and industry significance of the Stationery Drawer Organizer Market?
Our analysis indicates that the Stationery Drawer Organizer Market represents a critical sub-segment of workplace ergonomics and home organization, valued at $2.28 Billion in 2026. This sector encompasses specialized storage solutions ranging from acrylic inserts to modular wooden trays, facilitating efficient workspace management for commercial and individual consumers alike.
What are the key market drivers, restraints, challenges, and opportunities shaping the Stationery Drawer Organizer Market?
Growth is propelled by hybrid work models driving demand for ergonomic home office setups. However, supply chain bottlenecks for raw materials like virgin polymers and exotic hardwoods act as restraints. Strategic opportunities emerge in sustainable material sourcing, allowing manufacturers to capture eco-conscious segments through innovative bamboo and recycled plastic configurations.
Emerging trends and growth patterns in the Stationery Drawer Organizer Market
The shift toward minimalist home aesthetics has superintended a surge in demand for aesthetic storage solutions like transparent drawer inserts and bamboo dividers. Customizable modular systems dominate current purchasing patterns, as consumers increasingly prioritize adaptable desk accessories that integrate seamlessly with modern interior design trends.
How did the COVID-19 pandemic impact the Stationery Drawer Organizer Market and what is the recovery trajectory?
Pandemic-induced remote work mandates initially disrupted traditional B2B institutional sales while surging direct-to-consumer online purchases for home-office setups. Our research demonstrates a robust post-pandemic recovery trajectory, with supply chains stabilizing and corporate procurement budgets rebounding as offices implement hybrid return-to-work infrastructure.
Competitive benchmarking and strategic dynamics in the Stationery Drawer Organizer Market
The landscape features a blend of global conglomerates and specialized manufacturers. Industry leaders like 3M Company, IKEA, and The Container Store Group Inc. leverage expansive distribution networks, whereas regional players such as Acrimet Industria e Comercio Ltda. and Kuber Industries dominate localized markets through specialized product lines and agile supply chains.
Executive summary of key findings in the Stationery Drawer Organizer Market research
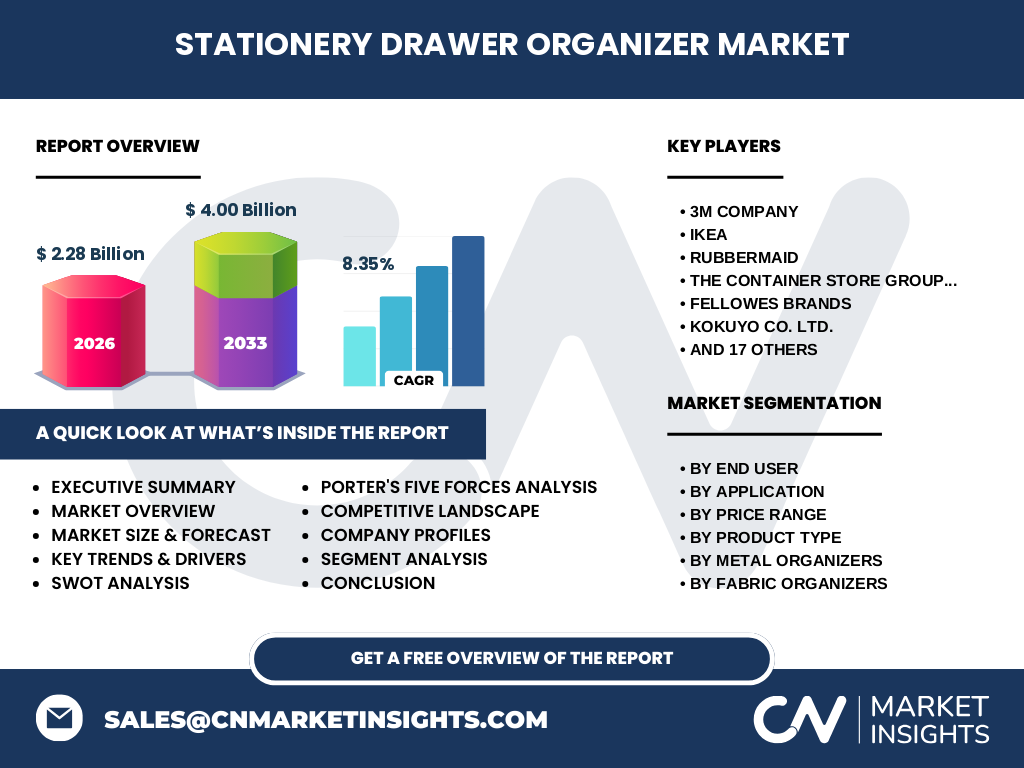
Driven by rising remote work adoption and ergonomic awareness, the market is poised for significant expansion. The data projects an acceleration from $2.28 Billion in 2026 to $4.00 Billion by 2033, registering a robust CAGR of 8.35%. Premium and mid-range segments lead revenue generation across global distribution channels.
Market forecast and growth trajectory for the Stationery Drawer Organizer Market from 2027 to 2033
Based on comprehensive trade data and macroeconomic modeling, the sector is set to expand rapidly, surging from its 2026 baseline to reach $4.00 Billion by 2033. This trajectory reflects a steady CAGR of 8.35%, underpinned by increasing commercial real estate investments and consumer spending on home organization.
Segmentation analysis across product types, applications, and price points
The market diversifies across multiple categories: Product Types include Plastic, Wooden, Metal, Fabric, and Other Organizers; Applications span Home, Office, and Educational Institutions; Price Ranges cover Economy, Mid Range, and Premium; while End Users feature Individual, Commercial, and Institutional buyers leveraging specialized distribution channels.
Regional market analysis and geographic distribution
Geographic performance varies significantly, with North America and Europe maintaining dominant revenue shares due to established corporate office infrastructure and high consumer spending power. Meanwhile, Asia-Pacific exhibits the fastest growth rate, fueled by rapid urbanization, expanding commercial office spaces, and rising disposable incomes in emerging economies.
In-depth regional review of key manufacturing and consumption hubs
Key manufacturing hubs are heavily concentrated in Asia-Pacific economies, leveraging cost-effective raw material sourcing and robust maritime logistics networks. Conversely, consumption patterns in North America and Europe heavily favor premium and mid-range eco-friendly organizers, with consumers prioritizing sustainable materials like bamboo and recycled metals.
Company profiles and strategic positioning of leading market participants
Major industry players strategically position themselves through product differentiation and omnichannel distribution. Brands like Rubbermaid, Sterilite Corporation, and Fellowes Brands focus on high-durability commercial solutions, while lifestyle-oriented brands like Poppin and Yamazaki capture urban consumer segments through design-forward, aesthetic stationery organization solutions.
Porter's Five Forces analysis of the Stationery Drawer Organizer Market
The industry experiences high competitive rivalry among established brands and numerous private-label alternatives. Buyer power is moderate to high due to the abundance of economical e-commerce options, whereas supplier power remains tempered by accessible raw material substitutes like plastics, engineered wood, and sheet metals.
SWOT analysis highlighting strategic strengths and market vulnerabilities
Key strengths include diverse product portfolios and established global distribution networks. Weaknesses involve vulnerability to raw material price volatility. Opportunities lie in untapped emerging markets and sustainable product innovations, while threats stem from counterfeit products and intensifying price competition across online retail platforms.
Value chain analysis from raw material extraction to end-user delivery
The value chain initiates with raw material procurement—sourcing polymers, steel mesh, bamboo, and textiles. This transitions into precision manufacturing and injection molding, followed by assembly and packaging. Distribution flows through Supermarkets Or Hypermarkets, Specialty Stores, and booming Online Stores to reach final consumers.
Investment insights and high-potential areas for capital deployment
Investors should target emerging opportunities in eco-friendly product innovations, particularly biodegradable composites and sustainable bamboo manufacturing. Companies incorporating advanced supply chain automation and direct-to-consumer digital marketing strategies present superior growth potential within the expanding mid-range and premium segments.
Conclusion and key takeaways for stakeholders and investors
The Stationery Drawer Organizer Market offers lucrative expansion prospects, backed by a projected 8.35% CAGR toward a $4.00 Billion valuation by 2033. Success in this landscape necessitates prioritizing sustainable material innovation, robust e-commerce positioning, and agile supply chain management to capture shifting consumer preferences.
Research methodology and baseline estimation techniques
Our analysis is constructed by triangulating primary stakeholder interviews with prominent industry executives, comprehensive trade registry data, and secondary macroeconomic indicators. Baseline estimates for 2026 are cross-verified using customs shipment records, manufacturing output metrics, and retail scanner data across major global markets.
Scope of the report, coverage parameters, and analytical limitations
This report covers global market sizing, segmental breakdowns, and competitive positioning from 2026 to 2033. Limitations include inherent forecasting uncertainties regarding macroeconomic shocks, regulatory shifts in international trade tariffs, and unexpected fluctuations in petroleum-based raw material costs impacting plastic organizer manufacturing.
Recent developments, corporate announcements, and strategic partnerships
Recent industry momentum is defined by strategic eco-friendly product launches and retail partnerships. Key players have increasingly invested in automated manufacturing lines for modular wooden and clear plastic trays, while expanding their direct-to-consumer digital footprints to bypass traditional retail intermediaries and enhance profit margins.